Imagine it. Rahul, 32, looking for finest term plan for 1 crore at 11 pm. Dozens of quotes occur. All of them call their plan “the best,” and some start at ₹500 a month and go up to twice that. He closes the tab, confused.
Sounds familiar? Not having enough plans is not the issue. Price is only part of the story. Premiums go up after year one, claim percentages are the same; ₹1 crore may not be adequate.
For example, a ₹1 crore term plan pays your family ₹1 crore if you die within the policy term. Starting at age 25, it costs about ₹7,000 a year. You’ll discover how to evaluate your cover, compare quotations fairly, read claim data and avoid costly mistakes.
Quick answer: Not every plan is best for everyone. At 30, ₹1 crore costs roughly ₹874 a month from year two. Claim ratios describe insurers, not plans. And ₹1 crore is enough only if your own sum says so: a sole earner with a loan may need ₹1.5 crore or more.
How This Guide Was Put Together?
- Prices and claim ratios: taken from Policybazaar’s listings on 26 October 2026, for a male non-smoker with ₹1 crore cover till age 60. Different premiums are shown for the first and second years.
- Rules (tax, GST, claim timelines): checked against IRDAI, the Income Tax Department, and the Department of Financial Services, and linked where used.
- What this is not: a quote-based comparison. None of the underwriters have purchased or evaluated these plans, so your actual premium may be different.
So, What Exactly Is a ₹1 Crore Term Plan?
How a ₹1 Crore Term Plan Works in Real Life?
Choose how long you want protection, say until 60, and pay a fixed premium each year. Should you pass away within those years, your chosen nominee receives the ₹1 crore. Nothing else is bundled in, which is why a ₹1 crore term plan counts as pure protection.
Expert tip from Finvest India: A term plan doesn’t build any savings, so you can’t borrow against it later.
What Does ₹1 Crore Life Cover Mean?
Think of 1 crore life insurance this way: if you’re gone, your family gets ₹1 crore. It can close a home loan, keep school fees paid and stand in for your lost paycheque. The main benefits of 1 crore term insurance are large protection for low cost, a generally tax-free payout and optional riders.
What If You Outlive the Policy?
If you outlive the term, the premiums are not refunded unless you opt for return of premium at a higher price. Since term insurance for 1 crore carries no investment element, its premiums stay well below those of endowment-style policies.
Best 1 Crore Term Insurance Plan in India: Insurers Side by Side
Treat this as a look at insurers, not a league table of plans. The ratios are for individual death claims, counted by number, for FY 2025–26. We took them from Policybazaar’s list on 26 October 2026. Premiums come next, because they shift with your age and term.
Insurer | Plan | Reported CSR (by number, FY 2025–26) |
Axis Max Life | Smart Term Plan Plus | 99.80% |
HDFC Life | Click 2 Protect Supreme Plus | 99.68% |
Canara HSBC Life | Promise 2 Secure – Level | 99.52% |
Tata AIA | Sampoorna Raksha Promise | 99.41% |
ICICI Prudential Life | iProtect Smart Plus | 99.30% |
Note: Don’t crown a winner over a 0.1–0.4 point gap. It’s tiny. You’ll also see different numbers for the same insurer on different sites, because the year and the way claims are counted can differ. Check each insurer’s latest disclosure before you buy.
Across the whole industry, IRDAI’s Annual Report 2024-25 records 97.82% of individual death claims paid by number and 96.29% by value. The second figure measures rupees paid out of rupees claimed. Use both as background, not as a prediction for your own claim.
How to Read These Claim Numbers?
- The ratio is about the company, not your plan: It shows how the insurer behaves overall, not how your policy will be handled.
- These figures cover every individual death claim an insurer gets, so endowment and ULIP claims are mixed in with term ones.
- You might see two different figures for one insurer on two websites. That’s usually the year, or how each site counts a claim as settled.
- Check the by-amount figure too: insurer-wise counts and values sit in IRDAI’s Handbook on Indian Insurance Statistics at irdai.gov.in, and in each insurer’s public disclosures.
How to Choose the Best Term Plan for ₹1 Crore?
Follow these steps in this order and choosing ₹1 crore term insurance gets a lot easier.
1. Test the Cover Against Your Real Needs
Work out your required cover before anything else. If it comes out above ₹1 crore, request quotes for a bigger sum.
2. Compare Quotes on Equal Terms
Give every insurer the same details: age, cover, term, payment mode and riders.
3. Study Claim Data
Look at the ratio by number and by amount. If a plan scores well on one but poorly on the other, dig further.
4. Judge the Insurer’s Strength
Check the solvency ratio (the regulator requires at least 1.5) and how smooth the claim process is.
5. Pick the Right Term Length
Age 60 is the usual end point. Extend it if loans or dependants will still be there after that.
6. Decide How You’ll Pay
Regular pay: you pay every year for the whole term. Limited pay: you pay for fewer years, but each year’s bill is bigger.
7. Check What’s Not Covered
Read the exclusions before you pay anything. We list what to check further down.
8. Lump Sum or Monthly Income
If the plan gives both, pick whichever your family will find easier to manage.
9. Weigh Optional Riders
Take only riders you’ll truly use, since each one adds to the premium.
Which ₹1 Crore Term Insurance Plan May Suit Your Needs?
No plan wins for everyone. Price, claim record, and features pull in different directions, so start with your own situation.
Your situation | Put this first |
Young, single, no loans | Price. Lock a level premium till 60. |
Parent with a home loan | Keep track of claims in order of amount, including any riders for severe sickness or premium waivers. |
Sole earner, kids under 10 | More cover (₹1.5 to ₹2 crore) and a monthly-income payout so the money lasts. |
Self-employed | Accurate proof of income and a premium that can be paid even in a slow year. |
Shortlist two or three plans, then compare them on equal terms.
Do You Think Your Family Needs ₹1 Crore in Term Insurance?
Factors That Determine Your Required Life Cover
So, is 1 crore term insurance enough? It depends on five things: your income, your dependants, your loans, future goals like your child’s education, and your savings or existing cover. Don’t count your employer’s group cover. Leave the job, and it ends.
How to Calculate the Right Term Insurance Cover
Cover needed = 10–15 times your yearly income + loans + future goals − savings and existing cover
This is only a rough screen. Inflation, spending, and the number of years of support all play a role in the final amount.
Example of Calculating Term Insurance Coverage
Say you earn ₹7 lakh a year.
- Income cover (10 times): ₹70 lakh
- Home loan: ₹30 lakh
- Child’s education: ₹20 lakh
- Minus savings: ₹20 lakh
- You need ₹1 crore.
With a ₹12 lakh income, the same sum comes to ₹1.5 crore. So ₹1 crore falls short.
Reviewer’s cross-check: The 10–15 times rule is a quick estimate, but it doesn’t explicitly count how many years your family needs support. Cross-check it: annually, divide household expenses by the number of years until your youngest child becomes self-sufficient, add loans and goals, and subtract your current assets. Use the bigger number. Example: ₹6 lakh × 15 years = ₹90 lakh before loans.
Worked Example: A 32-Year-Old Parent Selecting Cover
Take a sample father, 32, earning ₹12 lakh, with a ₹30 lakh home loan, a ₹20 lakh education goal, and ₹20 lakh saved.
- Cover: ₹1.2 crore plus ₹30 lakh plus ₹20 lakh divided by ₹20 lakh equals ₹1.5 crore, making ₹1 crore insufficient.
- Price: See the rows below for the age 30-35. Remember more cover costs significantly less than twofold.
- Shortlist claims: insurers strong by number and by amount.
- Payout: lump sum for the loan, monthly income for living costs.
- Rider: Waiver of premium.
₹1 Crore Term Insurance Premium by Age
The premium depends mostly on your age. Here are indicative quotes for a male non-smoker, cover till age 60.
Age | First-year premium | From year 2 |
25 | ₹586 | ₹666 |
30 | ₹691 | ₹874 |
35 | ₹911 | ₹1,035 |
40 | ₹1,195 | ₹1,513 |
Source: Policybazaar term insurance calculator, monthly premiums, 26 Oct 2026. Indicative only. Premiums vary by insurer underwriting and are not guaranteed quotations.
See the gap between the columns? Many insurers give first-year discounts, so budget for the year-two number.
Illustrative maths, assuming the year-two price stays level: At 25 you pay ₹6,763 + (34 × ₹7,685) = around ₹2.68 lakh over 35 years. At the age of 40, you will have to pay ₹13,738 + (19 x ₹17,390) = around ₹3.44 lakh for 20 years. Costs ₹76,000 extra and 15 less years of protection for waiting.
What moves your premium:
- Age: younger buyers pay less.
- Smoking: smokers pay more.
- Health: past illness or family history can raise it.
- Gender: women usually pay less. Some insurers list around 15% lower premiums for them.
- Job: risky work, like mining, can cost more.
- Policy term: a longer term costs more.
Find a cheap plan by making sure every quote has the same coverage, period, payment method, and riders. Everything that a good best term insurance plan for 1 crore calculator asks for, age, income, smoking status, duration, and payment mode, is consistent.
Who Is Eligible for a ₹1 Crore Term Insurance Plan?
- Age: 18+ can apply. Most insurers restrict entry to 60–65.
- Income and health: no income cutoff. Different insurers cap coverage based on income and previous plans. Age and coverage determine whether a medical exam is necessary. Poor health can increase your premium, add conditions, or require more testing.
- Salaried: don’t rely on office cover alone. Group cover ends when you leave the job and may be too small. Buy a policy in your own name.
- Self-employed: Term insurance for self-employed individuals works the same way, but insurers check income proof more closely. Expect to share ITRs and bank statements.You may wish to look at Section 6 of the Married Women’s Property Act, 1874. Where applicable the payout is to your wife and children solely and is protected from your creditors. Ask the insurer if the plan supports it, and take legal advice before relying on it.
- NRIs: You’ll usually need a passport, overseas address proof, and income documents. Some insurers need a medical test, which you may easily take abroad or by video.
How Can You Evaluate a ₹1 Crore Term Insurance Policy's Features?
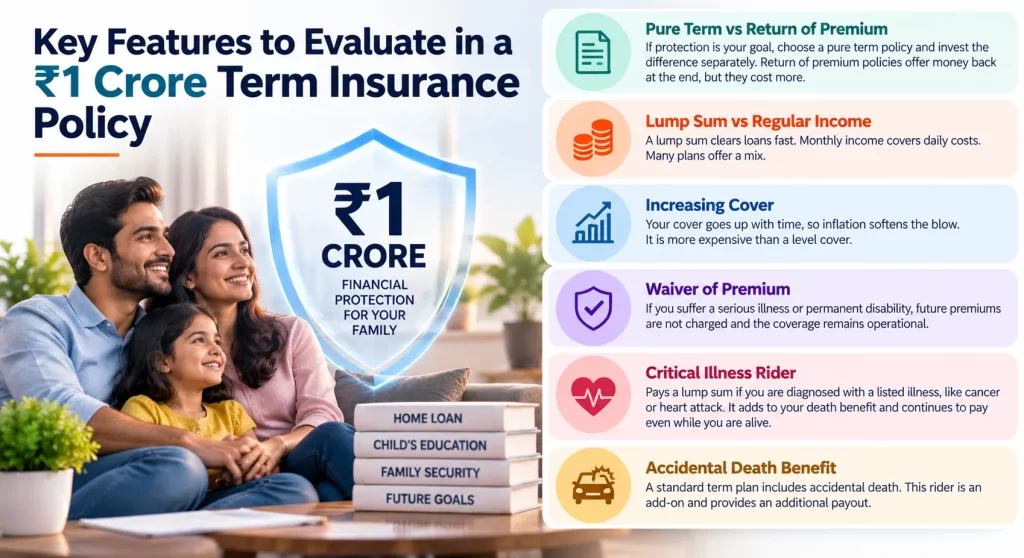
Not every plan has every feature below. Check each plan’s brochure.
- Pure term vs return of premium: If protection is your goal, choose a pure term policy and invest the difference separately. Return of premium policies offer money back at the end, but they cost more. If protection is your goal, go pure term and invest the difference separately.
- Lump sum vs regular income: a lump sum clears loans fast. Monthly income covers daily costs. Many plans offer a mix.
- Increasing cover: cover goes up with time, thus inflation softens the blow. It’s more pricey.
- Waiver of premium: if you suffer a serious illness or permanent disability, future premiums are not charged and the coverage remains operational.
- Critical illness rider: pays a lump sum if you’re diagnosed with a listed illness, like cancer or heart attack. It adds to your death benefit and continues to pay even while you’re alive.
- Accidental death benefit: standard plan includes accidental death. This rider is an add-on.
2026 Rule Changes That Affect Your ₹1 Crore Plan
- GST: Individual life insurance premiums have been GST-free since 22 September 2025. The Department of Financial Services says group policies still pay 18%.
- Income tax: The Income-tax Act 2025 came into force on 1 April 2026. Under the old tax structure, a section 123 deduction (up to ₹1.5 lakh a year on premium) is available, subject to several restrictions. With a few exceptions, the 2025 Income Tax Act generally exempts the death payout from taxation.
- Claims: The IRDAI’s Master Circular dated September 2024 says death claims should be paid within 15 days or 45 days if an inquiry is needed. Interest will be added to overdue payments at 2% above the bank rate. Deadlines for regulatory actions; not every case will have these dates.
- You get a free 30-day trial of a new policy before committing to it or canceling it. After accepting your proposal, the insurer has 15 days to issue the policy.
Your Family's Claim Kit: Set It Up Today
A ₹1 crore policy only helps if your family can claim it. Once your policy arrives:
- Provide the name, policy number, and insurance company’s number to your nominee.
- In a single folder, whether digital or paper, keep the policy PDF, most recent premium receipt, identification, and banking information.
- Say who calls the insurer first. The 15-day clock starts when the claim is intimated (45 days if investigated). Keep the acknowledgement.
- If a claim is delayed or disputed, complain to the insurer first, then Bima Bharosa.
What Should You Check Before Buying a ₹1 Crore Term Plan?
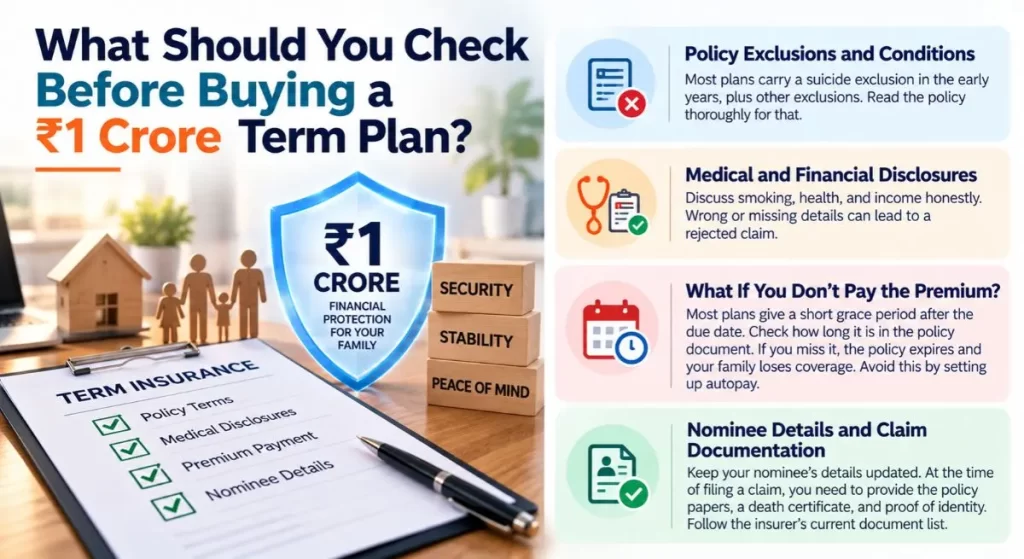
Policy Exclusions and Conditions
Most plans carry a suicide exclusion in the early years, plus other exclusions. Read the policy thoroughly for that.
Medical and Financial Disclosures
Discuss smoking, health, and income honestly. Wrong or missing details can lead to a rejected claim.
What If You Don’t Pay The Premium?
Most plans will provide you a little extra time after the deadline has passed. See how long it is in the policy document. If you miss it, the policy expires and your family loses coverage. Avoid this by setting up autopay.
Nominee Details and Claim Documentation
Keep your nominee’s details updated. At the time of filing a claim, it is necessary to present the policy papers, a death certificate, and evidence of identity. Follow the insurer’s current document list.
Expert Insights from Finvest India
Finvest India is a Bangalore advisory firm that started in 1999, and it has helped 500+ investors with life insurance. Its approach, in short:
- Get life insurance early: According to Prashasnth Jogimutt, the optimum time to acquire life insurance is in your 20s or early 30s when rates are at their lowest.
- Don’t begin with the product, start with the family: Put your debt, kids, and parents at the top of the list. After that, select the cover.
- Keep protection and investing apart: A term plan has no cash value, so you can’t borrow against it. That’s by design. Invest the rest separately.
- Know the limits: Understand coverage limits, waiting periods, and conditions before you choose.
- Before the claim day: prepare by making sure your nominee knows who to contact.
Disclosure: Finvest India is an IRDAI-licensed insurance agent (licence 02658) appointed with LIC of India, so it may not offer every plan above. Treat this as general guidance, not a plan pitch.
Common Mistakes to Avoid When Buying a ₹1 Crore Term Plan
- Picking cover without doing the sum.
- Choosing on price alone.
- Skipping the exclusions.
- Hiding a habit or illness.
- The duration is too short (if it finishes at 50, your 55-year-old self will be unprotected).
- Adding riders you won’t use.
What Documents Are Needed for a ₹1 Crore Term Plan?
The documents required for term insurance are few:
- ID proof: Aadhaar, PAN or passport.
- Address proof: Aadhaar, passport or a recent utility bill.
- Documents proving income: salary slips, Form 16, ITR or bank statements.
- Medical reports: only if the insurer asks.
Final Thoughts On A ₹1 Crore Term Insurance Plan
The best 1 crore term insurance plan is the one that fits your numbers. Do the cover sum first. Compare quotes on equal terms. Then buy early and answer every form question honestly. That’s how you choose the best term plan for 1 crore.
Run your cover sum first, then compare quotes on equal terms. If you’d like help with the shortlist, Finvest India’s team can walk you through it.